Andalucía has just posted the busiest mortgage month in its history, and it happened in the same month the Euríbor turned upward. The INE counted 9,321 mortgages on homes across the region in June, 15.7 per cent more than in June 2025 and comfortably the highest figure of any autonomous community in Spain. The Andalucía mortgage market has been growing quietly for months, and June was the month it overtook everyone.
The timing is what makes the Andalucía mortgage market interesting. Mortgages are signed on confidence and paid on rates, and June was the month the twelve month Euríbor, the index most Spanish variable loans are priced on, climbed to its highest level in over a year. More capital was lent, at higher average amounts, in more loans, than at any point this year, and the Andalucía mortgage market did it while the national average grew at barely two thirds of its pace. Reading those two facts together says more about where this market is going than either does alone.
Andalucía led Spain’s mortgage market by a wide margin
The INE’s mortgage statistics for June record 9,321 home mortgages constituted across the Andalucía mortgage market, a rise of 15.7 per cent on the year. That is 20.3 per cent of the 45,907 mortgages signed in Spain that month, roughly one in every five, and it puts the region ahead of Cataluña on 8,045 and Madrid on 6,976. Andalucía’s growth rate also ran almost five points clear of the national average of 10.8 per cent.
The money followed the volume. The average mortgage reached €178,365, up six per cent on the year and a record for the series, and the total capital lent on home mortgages across Spain in June came to €8,188 million, 17.5 per cent more than in June 2025. Families are not only borrowing more often. They are borrowing larger amounts, and the Andalucía mortgage market absorbed it without a stutter. June’s figures are a photograph of a market in motion, and the rest of this post reads what that photograph contains, region by region and rate by rate.

The June figures line by line
Beneath the volume of the Andalucía mortgage market sit the terms, and they are worth reading carefully. Of the home mortgages signed in Spain in June, 61.7 per cent were fixed rate and 38.3 per cent variable. The average initial interest rate across all new mortgages settled near 2.89 per cent on fixed products against 3.07 per cent on variable ones, a gap of less than two tenths of a point.
That narrow gap is the quiet story of the month. Fixed rates carry certainty, and for most of the past two years they also carried a visible premium, because banks priced in the expectation of falling rates. With the Euríbor now climbing, that premium has all but disappeared, and borrowers are getting the insurance of a known payment for very little extra cost.
The Euríbor has turned upward
The twelve month Euríbor, the reference for the vast majority of Spanish variable mortgages, stood at 2.952 per cent in August according to the Banco de España’s official series, 0.840 points higher than in August 2025. The climb has been steady rather than sudden: the index spent the spring in the low twos, reached 2.855 per cent in July, and moved higher again in August.
For a household in the Andalucía mortgage market on a typical variable loan, the arithmetic is concrete. A €150,000 mortgage over twenty five years with a one point spread over the Euríbor was paying around €720 a month at the August 2025 rate. Reset at the August 2026 rate, the same loan costs around €788, roughly €68 a month more and more than €800 across a year.
It is a real cost, and it is nothing like the shock of 2022 and 2023, when the index ran from negative territory to above four per cent in under two years. Any buyer weighing a variable offer against the Andalucía mortgage market’s record volumes should price that difference into the first year of ownership, then decide.

Rising rates on the Costa del Sol
The practical effect lands in three places. Fixed rates, already the majority choice, now cost almost the same as variable products, which makes the certainty argument for itself. Cash buyers gain a little more negotiating weight against anyone depending on leveraged finance, a dynamic the prime segment here has shown for years. And buyers structuring off plan purchases with staged payments can lock the bulk of their financing closer to completion rather than committing a rate at reservation, which is worth real money when the reference rate is moving.
Each of those pushes in the same direction, towards a decision made with the numbers in front of you rather than a feeling about rates. The off plan guide covers how staged payments actually work, the requirements form starts a search shaped around your budget and financing, and the deeds on any street you are considering are records we already hold.
JUST Real Estate has tracked sold data over many years and has compiled the JUST Intelligence Database™, which holds data no other agency has. We can accurately compare your property to neighboring sales and stats, so our competitive market analysis gives you the advantage in a buyer’s market.
The Andalucía mortgage market and the Costa del Sol buyer
Context from the rest of the site helps here. The province level picture sits in our Málaga second quarter report, the coast’s price record in the Costa del Sol market report, and the towns themselves in the Marbella guide and the Marbella property page, because a mortgage conversation in this region always starts with which town, and which street, is actually being financed.
A mortgage in Marbella, Estepona or Benahavís rarely looks like the national averages of the Andalucía mortgage market, because the buyer base here is structured differently. International buyers use cash, finance arranged at home, or Spanish products aimed at non residents, which typically lend a smaller share of the price at a slightly higher rate than residents receive. The record Andalucía mortgage market figures describe the region’s volume, not the terms a Costa del Sol buyer will be offered.
What the region’s volume does describe is demand. While national housing transactions fell 5.7 per cent in the second quarter according to the Colegio de Registradores, the second consecutive quarterly decline, mortgage lending in Andalucía moved the other way. Buyers who need finance were still here, still signing, and signing in greater numbers than anywhere else in the country, which is the strongest available signal that the region is absorbing a disproportionate share of Spain’s active demand.
The Euríbor is the cost side of the Andalucía mortgage market story, and June’s record volume is the demand side. Both were true in the same month, and neither cancels the other.

Fixed or variable after two months of climbs
For much of 2025 the answer to the fixed or variable question was patient: sign variable, let the falling Euríbor bring each review down. Two consecutive monthly climbs have flipped that calculation. A borrower signing variable today is betting on the index resuming its decline within their first review period, while a fixed rate now costs almost the same as the variable alternative at signing.
The Banco de España’s August rates put the fixed versus variable choice in the Andalucía mortgage market into perspective. Fixed products averaged 2.89 per cent in June against 3.07 per cent for variable loans, and with the Euríbor at 2.952 per cent and climbing, a fixed payment at 2.89 now insures against exactly the move every variable borrower has just lived through. Insurance that cheap has a way of looking wise twelve months later.
For the Andalucía mortgage market as a whole it is a headwind worth watching, and for an individual seller it is a reason to have the payment and pricing conversation before the buyer does. The Andalucía mortgage market has seen both regimes inside a decade, and the borrowers who fared best through the last switch were the ones whose structure was decided before the move, not after it. For the Andalucía mortgage market as a whole it is a headwind worth watching, and for an individual seller it is a reason to have the payment and pricing conversation before the buyer does.
How the deed gap shapes an asking price
Sellers on the Costa del Sol should read the same data in their own favour, because a market signing record mortgage volume is a market with buyers ready to complete. The discipline sits on the pricing side: an asking figure set on the portal average invites a negotiation against deeds the seller has never seen, and the Andalucía mortgage market’s own numbers show asking prices running well ahead of achieved ones across the province.
The way through is the comparable set. Our seller service prices against the deeds on your own streets, the valuation calculator gives the quick reference, and the gap between asking and achieved on your specific property is exactly the number our records hold. A record month is a good month to sell, priced properly.
The record behind the average
The Andalucía mortgage market’s average of €178,365 sits far below the price of a typical home in Marbella or Benahavís, and that gap is composition rather than contradiction. The regional figure blends inland apartments with coastal villas, and buyers at the upper end of this coast borrow a smaller share of the price or none at all. The average describes the volume of the Andalucía mortgage market. The deeds describe its price, and on this coast those two numbers live further apart than anywhere else in Spain.

For anyone financing on the Costa del Sol, the practical reading is simple. Money is available, the region is signing more of it than anywhere in Spain, and the reference rate has started rising, which makes the structure of a purchase matter more than it did in spring. The buyers guide walks the process end to end, the Marbella market report carries the quarter’s prices, and our own deed records set specific streets against specific comparables before any offer is made.
Straight answers on Andalucía mortgages
How many mortgages were signed in Andalucía in June 2026?
The INE recorded 9,321 mortgages on homes across the Andalucía mortgage market in June 2026, up 15.7 per cent on the year and the highest figure of any autonomous community, ahead of Cataluña and Madrid.
What is the average mortgage in Andalucía?
The average mortgage reached €178,365, up six per cent on the year. The regional figure blends everything from inland apartments to coastal villas, so a specific street should always be priced on its own comparable sales.
What is happening to the Euríbor?
The twelve month Euríbor stood at 2.952 per cent in August according to the Banco de España, 0.840 points higher than a year earlier. Variable borrowers across the Andalucía mortgage market are seeing the difference arrive at their annual reviews.
Are more Spanish mortgages fixed or variable?
Fixed rate products took 61.7 per cent of new home mortgages in June, against 38.3 per cent variable, and with fixed initial rates at 2.89 per cent against 3.07 per cent for variable, the premium for certainty has narrowed to almost nothing.
Is it still a good time to buy property in Andalucía?
The region signed more home mortgages than any other community in Spain in June while national transactions fell, which points to demand that outruns the national trend. The right purchase still depends on the street and the comparable deeds, which is the analysis we do before anything else.
The Costa del Sol property market continues to evolve, but informed decisions begin with reliable data. Download the JUST Q1 2026 Marbella Property Market Report today and gain exclusive insight into one of Europe’s most resilient and internationally driven residential markets.

DOWNLOAD OUR Q1 2026 MARKET REPORT NOW
Research enquiries:
James Evans — Managing Partner
📞 +34 643 390 376 | ✉️ james@justrealestate.es
Sales enquiries:
Alina Nouaimeh — Partner
📞 +34 600 689 749 | ✉️ alina@justrealestate.es
FAQ
Is the JUST Market Report free to download?
Yes. The report is available as a complimentary download and provides professional analysis of the Marbella, Estepona and Benahávis property markets.
Who is the report designed for?
The report is written for buyers, sellers, investors, developers, relocation clients, family offices and anyone seeking accurate, data-led insight into the Costa del Sol property market.
Where does the data come from?
Our analysis uses official information from Registradores de España, INE, Notariado, Tinsa, Banco de España and other recognised industry sources, combined with our own market observations and research.
How often is the report updated?
JUST Real Estate publishes a comprehensive market report every quarter, ensuring readers have access to the latest available market intelligence.
Our latest listings
View our latest listings of luxury properties for sale, where sophistication and comfort come together for an exceptional living experience.
5 bedroom villa for sale in Mijas
- 5 beds
- 6 baths
- Plot: 1,805 m²
- Interior: 465 m²
4 bedroom villa for sale in Mijas Pueblo, Mijas
- 4 beds
- 4 baths
- Plot: 580 m²
- Interior: 150 m²
4 bedroom villa for sale in Mijas
- 4 beds
- 4 baths
- Plot: 580 m²
- Interior: 150 m²
6 bedroom villa for sale in Mijas
- 6 beds
- 4 baths
- Plot: 658 m²
- Interior: 360 m²
5 bedroom house for sale in Valtocado, Mijas
- 5 beds
- 4 baths
- Plot: 41,000 m²
- Interior: 378 m²
4 bedroom villa for sale in Mijas Pueblo, Mijas
- 4 beds
- 4 baths
- Plot: 1,974 m²
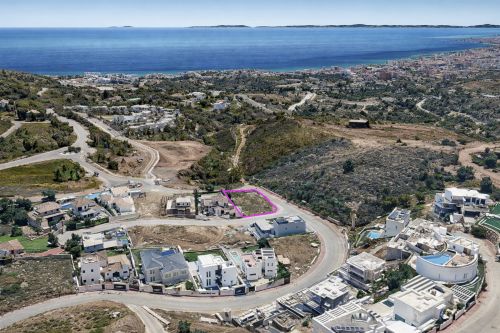
Plot for sale in Loma del Flamenco, Mijas
- Plot: 847 m²